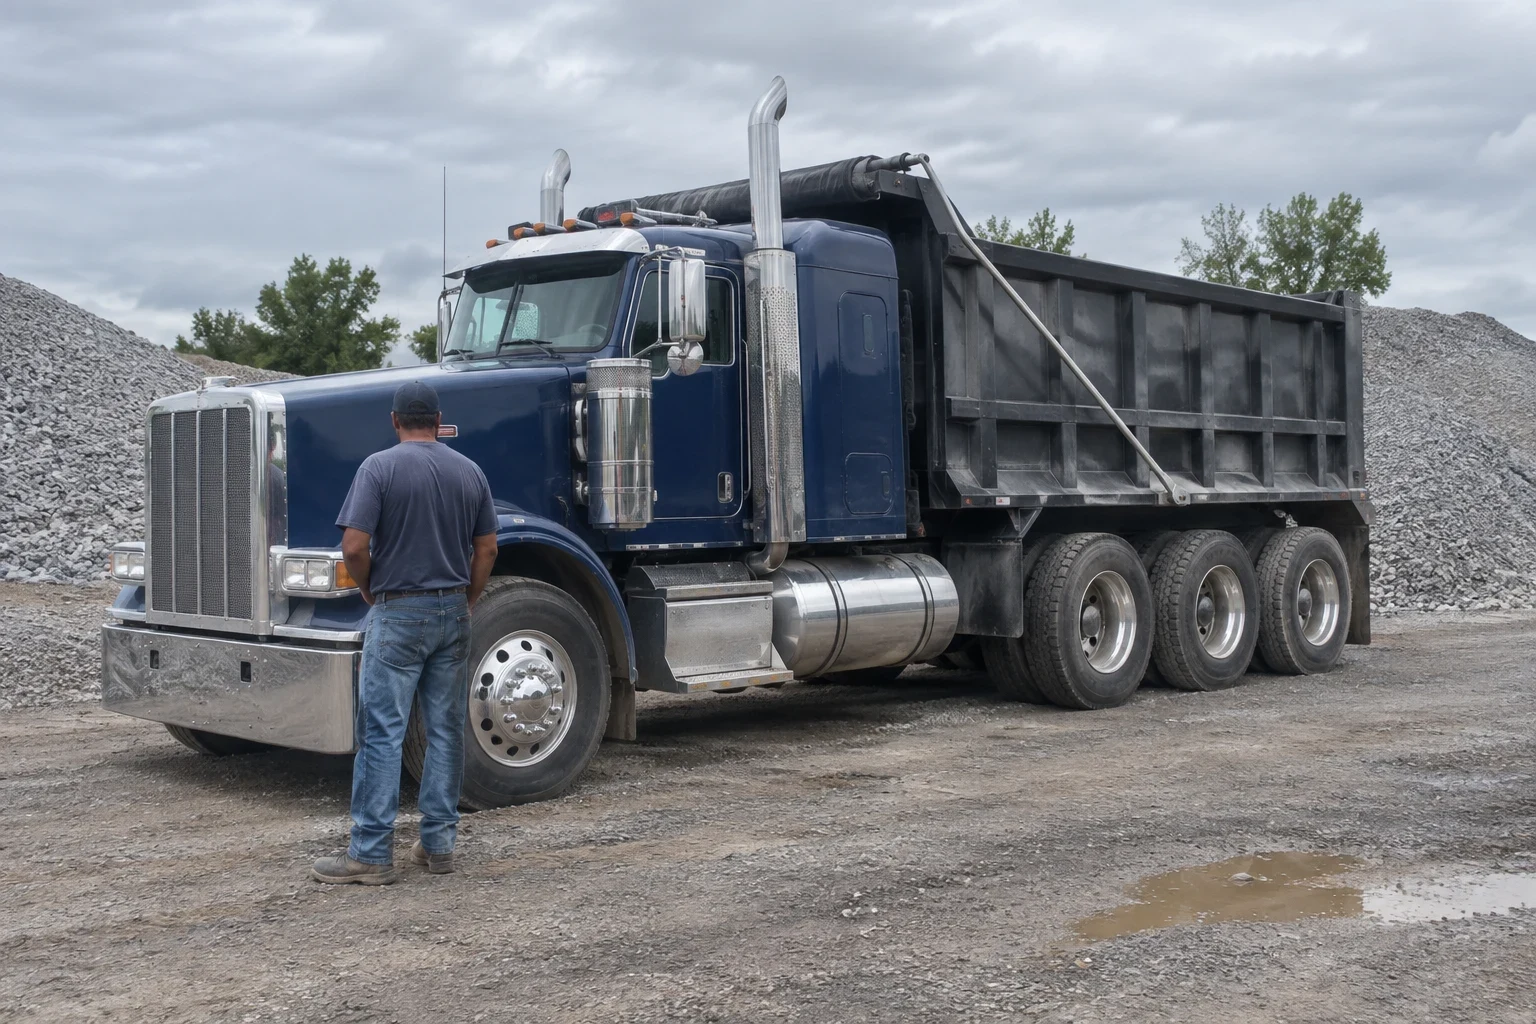
ServicesDump Truck Insurance
Dump Truck and Construction Truck Insurance in Mesquite
We write coverage for tri-axle dumps, end dumps, belly dumps and the trucks that haul your equipment. Tell us what you haul, how far and for whom. We build a policy that matches those answers, so your certificates are ready before the job starts.
Why dump and construction trucks need their own kind of policy
A dump truck does not run like a van hauling freight. It loads at a pit, runs short loops on rough ground, raises a hydraulic bed on uneven fill and often leaves pavement entirely. Insurers rate that exposure differently, and a policy written as general freight can leave gaps exactly where your trucks spend their day.
We start with how your operation actually works: the commodities (sand, gravel, caliche, base, demolition debris), your radius, whether you run intrastate under a Texas registration or interstate under MC authority, and what your contracts require. From there we line up primary auto liability, physical damage and, where it makes sense, motor truck cargo coverage.
The aim is to have this settled well before renewal or bid season, not the morning a superintendent refuses to let your truck through the gate.
Coverage built into a dump truck policy
- 01
Liability for harm to others
If your truck injures someone or damages a car, a fence or a building, primary auto liability responds. Your state or federal filing attaches to this coverage, and contractors frequently ask for limits above the filing minimum.
- 02
Chassis, body and trailer protection
Collision and comprehensive cover the truck, the dump body and any end-dump or transfer trailer. We base the stated value on true replacement cost, with the body and hoist counted in.
- 03
Upset losses while dumping
A raised bed on soft fill or a side slope is where many dump trucks go over. We read how each carrier's form handles an upset so you have the answer before it ever matters.
- 04
Cargo coverage where loads call for it
Dirt and rock haulers often can skip cargo coverage. Moving equipment, pipe or materials that belong to someone else usually changes that, and we tell you straight which group your loads fit.
- 05
Contract endorsements and certificates
General contractors often want their company named on your auto policy along with a waiver of subrogation in their favor. We add those endorsements and send a certificate of insurance worded the way the contract asks.
Questions about Dump Truck Insurance?
Call(972) 846-9540When your dump truck coverage may not fit the work
A certificate came back from a GC
A general contractor returning your certificate of insurance for short limits or missing endorsements is a strong hint the policy was never set up for construction contracts.
You are rated as general freight
A dump operation written as dry freight can carry the wrong vehicle class, commodity list or radius. That kind of mismatch tends to surface when a claim is filed.
A new truck or driver joined
Every added unit and every new driver belongs on the schedule before the first load. A truck running without being listed is a coverage gap, not paperwork to catch up on.
Loads now cross the state line
Runs into Oklahoma or Louisiana take you out of Texas intrastate rules and into interstate ones, which means MC authority and a federal liability filing.
Stated values have not changed in years
Replacement costs for dump bodies and hoists keep rising. An old stated value leaves a total loss paying well short of what a replacement truck costs.
From first call to certificates in hand
- 1
Walk us through the operation
On the phone, over video or in our office, you tell us about the trucks, trailers, materials, radius and contracts. Getting those details right at the start avoids weeks of fixes later.
- 2
Pulling the documents together
We gather your DOT number, VINs, driver list with license information, current declarations pages and loss runs. For a newer operation, we list the filings you will need.
- 3
Matching you with carriers that write dump work
Plenty of insurers decline aggregate and construction haulers. We place your file with the ones that accept them and compare policy forms side by side, not just the premium.
- 4
Going through the quote together
We cover limits, deductibles, exclusions, upset losses, off-road use and hired trucks one by one, so nothing catches you off guard once the policy is bound.
- 5
Binding and filings
When you pick a quote, we bind the policy, have the carrier file your state or federal proof of coverage and send certificates to every contractor you name.
Factors behind a dump truck premium
A dump truck premium reflects how the work gets done as much as the truck itself. Pit-to-site loops close to the yard rate differently from long hauls, and every driver's record carries real weight. Knowing these factors months before renewal gives you time to budget and to fix the ones you can control.
- Radius and what you haul
- Short aggregate runs, demolition debris and equipment moves each bring a different risk profile. A wider radius or a mix of load types usually pushes the rate up.
- Who is behind the wheel
- Underwriters pull motor vehicle records and look at years of CDL experience for each driver. A single driver with recent violations can raise the price for the whole policy.
- Truck value and age
- The physical damage portion is priced on what the chassis, dump body and trailer are worth. Covering a late-model quad-axle with a high-lift body costs more than covering an older single-axle unit.
- Claims and inspection history
- Past losses and your FMCSA roadside inspection results both feed into underwriting. A few clean years is the strongest lever you have on price.
- Contract terms
- Higher liability limits, naming a contractor on your policy and waivers of subrogation can each add to the premium. We build them into the quote from the first conversation so the number holds.
Dump truck insurance questions
Do I need MC authority to haul dirt and gravel?
Only if you haul across state lines or for hire in interstate commerce. Most dump trucks working around Mesquite run intrastate, which calls for a USDOT number and Texas registration with a liability filing instead. We confirm which applies to your routes before we quote.
Is my truck covered on a job site, off the pavement?
Auto liability and physical damage typically follow the truck onto a job site, but some forms limit off-road use or exclude certain operations. We read that language with you so you know where the coverage stops.
Will physical damage pay if my truck tips while dumping?
Many policies treat a tip-over as an upset or collision loss, subject to your deductible. Some carriers add conditions, so we point out exactly how each quote handles it.
Can I add a truck when a new contract starts?
Yes. Call us before the truck goes to work with its VIN, value and the driver, and we add it to the schedule and update your certificates. Planning that a few weeks ahead keeps the start date on track.
I am an owner-operator leased to a hauling company. What do I need?
Usually the hauling company carries primary liability, and you carry physical damage plus non-trucking liability (bobtail) insurance. We review your lease to see who is responsible for what.
Get your trucks covered before bid season
Tell us about your trucks, your loads and the contracts coming up. We will lay out the coverage and the certificates you need, with time to spare.